Supreme Court examines limits of lawyer-client privilege in tax probes.
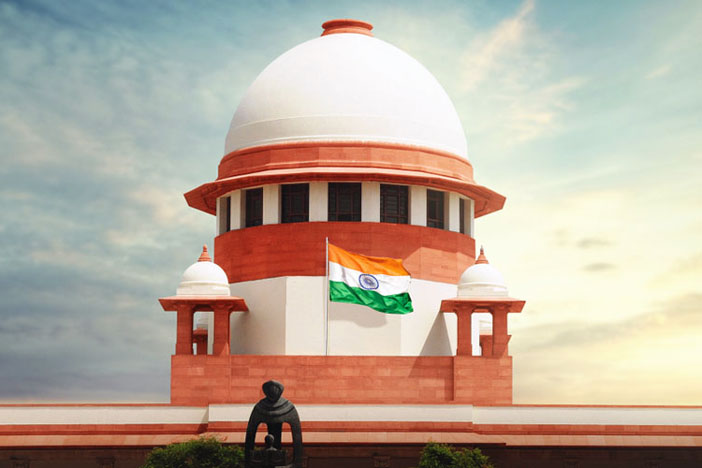
Supreme Court of India.
The Supreme Court has raised questions over how far lawyer-client privilege should extend when tax authorities investigate matters involving suspected tax evasion or avoidance, stressing the need for a workable way to distinguish confidential legal advice from communications connected to unlawful activity.
A three-judge Bench comprising Chief Justice of India Surya Kant and Justices Joymalya Bagchi and V Mohana examined the issue on 24 September while hearing a suo motu case concerning summons issued by investigating agencies to advocates who provide legal opinions or represent parties during criminal investigations.
At the heart of the proceedings is a question with implications for both lawyers and their clients: when can a communication between them remain confidential, and when can authorities require it to be disclosed?
The Court’s discussion indicated that not every communication relating to taxation can automatically be treated in the same way.
Tax planning versus tax avoidance
Justice Joymalya Bagchi used taxation to illustrate the difficulty faced by authorities when determining whether a communication is protected by legal privilege.
He pointed to a distinction between legitimate tax planning and impermissible tax avoidance.
“Let us say, (a lawyer who is questioned) says, ‘No, no, this is not tax avoidance. This is tax planning.’ Then that exchange will become protected. The problem is how the Income Tax authorities are looking at it,” Justice Bagchi said.
The observation highlights the challenge involved in drawing a practical boundary.
A lawyer may advise a client on how to structure transactions or affairs within the law so that the client takes advantage of available legal provisions. Such advice can form part of legitimate legal consultation.
The situation becomes more complicated when communications concern arrangements intended to evade legal tax obligations or otherwise facilitate unlawful conduct.
The Court indicated that there needs to be a mechanism capable of separating the two categories rather than treating all tax-related communications in the same manner.
“We have to see a way which is workable,” Chief Justice Surya Kant said.
Justice Bagchi agreed with the need for such an approach, while raising concerns about the manner in which Income Tax authorities currently examine these communications.
“Absolutely right. But not the way the Income Tax authorities are looking at it,” he said.
Why the distinction matters
Lawyer-client privilege is intended to protect the confidentiality of communications made for the purpose of obtaining legal advice. The protection allows clients to communicate openly with their lawyers, while enabling lawyers to understand the complete circumstances of a matter before providing advice.
Tax investigations can, however, involve documents and communications that sit close to the boundary between legal advice and evidence of potentially unlawful conduct.
The Supreme Court‘s discussion suggests that identifying the character of a communication may be necessary before deciding whether it should receive protection.
The issue is particularly significant because a communication may contain both legal advice and information concerning a transaction under investigation. Determining whether the privilege applies therefore cannot always be reduced to the identity of the people involved or the fact that a lawyer was part of the exchange.
Court also examines role of in-house counsel
 The Bench also considered whether communications involving in-house counsel should receive the same treatment as communications with external lawyers.
An in-house lawyer is employed by the company and has an employer-employee relationship with the organisation. An external lawyer, by contrast, is engaged under a professional arrangement to provide legal services.
Justice Bagchi noted this distinction while the Bench considered the scope of privilege available to communications involving in-house counsel and their corporate clients.
The question is significant for companies because legal departments routinely advise management on matters involving taxation, regulatory compliance, contracts and potential disputes.
The Court’s deliberations indicate that the professional status and relationship of the lawyer may have a bearing on how privilege is considered.
READ: Dalmia Cement Expands Empire with Major Acquisition from Jaiprakash Associates
Earlier Supreme Court judgment comes under discussion
Senior Advocate Mukul Rohatgi also raised concerns about the implications of an earlier Supreme Court judgment dealing with the issue.
According to Rohatgi, the earlier decision did not adequately address lawyers who independently advise companies but are not employed as in-house counsel.
He also submitted that the earlier judgment did not sufficiently consider the relevant statutory provisions, apart from its operative portion.
Rohatgi informed the Bench that the General Counsel’s Association has filed a review petition challenging aspects of the earlier judgment.
He requested the Court to examine the issue in that context as well.
Supreme Court seeks a practical framework
The proceedings are therefore examining more than a narrow question about tax investigations. They involve the broader principles governing confidential communications between lawyers and clients when investigative agencies seek information.
For tax authorities, the challenge is to investigate suspected violations effectively without treating legitimate legal advice as evidence merely because it concerns tax arrangements.
For lawyers and clients, the issue concerns the circumstances in which communications made during the process of obtaining legal advice can remain confidential.
The Supreme Court’s observations point towards the need for a practical framework that can distinguish lawful tax planning from communications connected with impermissible tax avoidance or other unlawful conduct.
The Bench has not, on the basis of the proceedings described, laid down a final test resolving every such situation. Instead, its questions have focused on how such a distinction could be made in a manner that is workable in actual investigations.
As the Court considers the wider issue of summons to lawyers and the protection available to professional communications, its examination of tax-related advice could have implications for how legal privilege is understood in investigations involving companies, lawyers and regulatory authorities.
Don’t Miss: UP Tenancy Act 2021: Allahabad High Court Strikes Down Key Provisions